D07 – Digital ad inventory has exploded. Where does that leave news publishers?
As digital platforms multiply and capture more of consumers’ time, news publishers are being pushed to rethink an advertising model built around inventory, traffic and programmatic
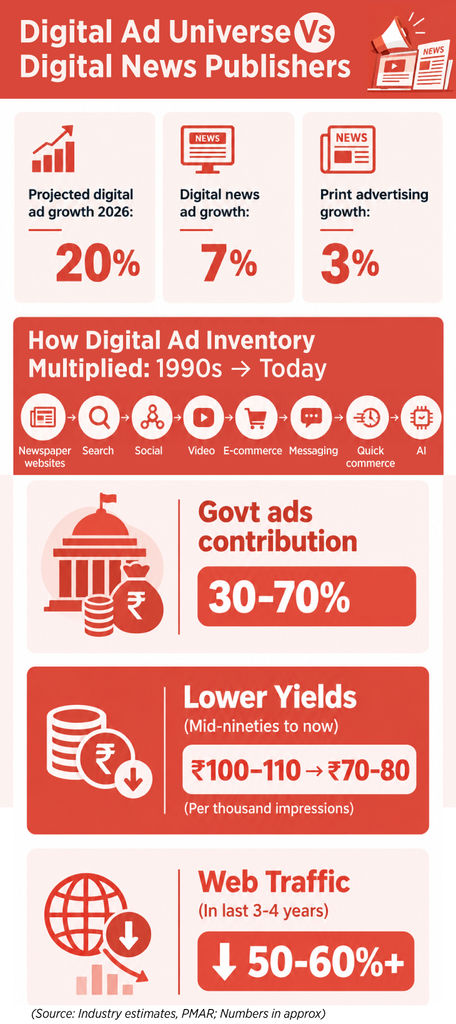
For two decades, India’s digital advertising market has expanded by adding one new pool of inventory after
another. What began largely with newspaper publishers’ websites in the 1990s has since expanded to search,
social media, video, e-commerce, messaging, retail media, quick commerce and a growing number of digital
platforms.
The supply of digital ad inventory, therefore, has grown many-fold. But the same cannot be said about the amount
of inventory that news publishers can create from journalism. That imbalance is emerging as an important, and
less discussed, reason why digital advertising growth has not translated proportionately into revenue for news
publishers.
“Digital advertising inventory has expanded exponentially over the past two decades as new platforms and
business models have emerged,” says Pradeep Gairola, Business Head, The Hindu Digital. “In the early days of
the internet, news publishers were among the primary sources of digital advertising inventory. Then came Google
and Meta, followed by other social platforms, e-commerce marketplaces, apps such as Truecaller and Telegram,
quick-commerce platforms, and now AI platforms. Advertisers today have an almost limitless range of digital
environments in which to spend. For news publishers, this means competing for advertising dollars in a market
where the supply of inventory has grown far faster than demand.”
The structural problem is therefore not simply that digital advertising has moved to Big Tech. It is that the
definition of digital advertising itself has expanded far beyond the inventory news publishers can realistically
generate.
Print media advertising grew 3% to ₹20,866 crore in 2025 from ₹20,272 crore in 2024, according to PMAR 2026.
Digital news platforms, however, have seen relatively modest growth across most large media houses. Even when
display advertising and brand solutions are combined, industry growth is estimated at around 7–8% —
significantly below the roughly 20% growth estimated for India’s overall digital advertising market.
Globally, digital circulation and advertising contribute 31% of the revenue, according to WAN-IFRA’s latest World
Press Trends Outlook, based on more than 170 senior media executives across 66 countries.
Meanwhile, Search, performance advertising, retail media and commerce-led formats have become major engines
of digital ad growth, while display advertising — historically one of the principal sources of monetisation for news
websites — remains a relatively weaker part of the market.
Stagnant ad rates
For most digital publishers, government advertising accounts for 30–70% of total ad revenue. While Big Tech
platforms have steadily increased their ability to command higher ad rates, DAVP rates for news publishers have
seen muted growth, further widening the monetisation gap, industry leaders say.
Publishers point to government advertising as another example of how news inventory is valued. Publishers argue
that they deserve better DAVP rates than Truecaller and Telegram, which are currently at par with news
publishers.
“Government advertising rates need to better recognise the difference between news publishers on the one hand
and digital platforms and content creators on the other,” he says. “News publishers invest significantly in original
journalism, editorial standards and brand trust. Advertising alongside that journalism should not be valued
simply as another unit of digital inventory.”
Gairola also points to the longer-term erosion in digital advertising yields. “In the mid-1990s, digital advertising
CPMs — the price paid per thousand ad impressions — were around ₹100–110. Thirty years later, many of India’s
leading news publishers operate at average yields of only around ₹70–80. For years, publishers could absorb this
erosion in pricing because page views and advertising volumes were growing rapidly. That equation has now
changed. Over the past four to five years, many large publishers have seen their traffic decline by more than 50%,
and the outlook for referral traffic remains challenging. In this environment, publishers have little choice but to
protect advertising yields as much as possible while simultaneously building new sources of revenue.”
Limits of News Consumption
Sandeep Amar, founder, pdlab.in, an adtech company, argues that the money has followed attention and time
spent, with much of that attention now sitting on tech platforms. “The bad part is that display advertising, which
is what funds news, is the weakest part of the digital market. The growth is all in search, performance and retail
media, and that is Google, Meta and Amazon territory,” he says.
That creates a difficult equation for publishers. They can increase traffic, but they cannot increase the number of
hours in a day that consumers spend consuming news. And even when audiences grow, the inventory may not
command the same value as a search query, a commerce transaction or a highly targeted social-media impression.
According to the Ormax OTT Audience Report 2026, India watches an estimated 517 billion hours of digital
videos in a year (14.9 hrs per week), across social media, YouTube, OTT apps, micro dramas, and FAST channels.
News constitutes a minuscule share of this universe, observers say.
Abhishek Karnani, Director, Free Press Journal Group of Newspapers, believes this calls for a fundamental shift
in how publishers define their advertising business.
“News is only one part of a consumer’s digital attention, often accounting for just 10–15 minutes of the entire
day,” says Karnani, who is also President of the India Chapter of the International Advertising Association (IAA).
“Consumption has moved across social media, video, gaming and messaging. Publishers therefore need to look
beyond traditional digital advertising and programmatic and explore branded content, events, experiential
partnerships and communities to create greater value for advertisers,” he noted.
The distinction is important: the problem may no longer be a shortage of audience, but the limited economic
value being extracted from each audience relationship.
From Inventory-Led to Value-Led
Karnani describes the shift as moving “from an inventory-led model to a value-led model”. “The question is no
longer simply how we get more traffic, but how we create more value from the audience we have built,” he says.
That could mean using first-party data to build stronger audience cohorts, packaging editorial audiences for
brands, developing communities around specialised interests, or combining digital reach with events, branded
content and other high-value formats.
Amar takes the argument further. He says publishers need to become more sophisticated in how they present
their audiences to advertisers, including through stronger customer data platforms (CDPs) and potentially
industry-level data collaboration.
“News publishers need to represent themselves in a scientific manner, with proper CDPs to brands,” he says,
suggesting that publishers could explore CDP consortiums that aggregate audiences across multiple publishers.
The idea addresses one of the fundamental disadvantages publishers face in the current market: individual
publishers may have large audiences, but platforms have the scale, data infrastructure and technology to make
those audiences highly addressable.
The challenge is not merely building more traffic, therefore. It is turning fragmented traffic into an identifiable,
measurable and commercially valuable audience.
Big Tech Revenue Share
The discovery problem becomes even more complicated as AI-led search and changing platform algorithms alter
the traditional route from audience to publisher. Most news sites have lost half of their web traffic over the past 3-
4 years. For publishers, the risk is that they continue to supply the journalism while platforms increasingly own
the discovery layer, audience data and monetisation infrastructure.
Globally, publishers’ 90-95% digital ad revenue comes via programmatic with Google having the lion’s share.
Clearly, direct sales has miniscule share which further skews the equation towards Big Tech who keep 15-40% of
revenue share depending on whether ads are displayed at publisher’s platforms or at their platform such as
YouTube and Instagram, industry leaders noted.
Sujata Gupta, Secretary General and CEO, Digital News Publishers Association (DNPA), says the imbalance is
structural. “Publishers invest in journalists, original reporting, fact-checking and editorial accountability, but a
significant share of the advertising value generated around their content is captured by technology platforms and
intermediaries,” she says.
She argues that publishers have limited visibility into how advertising revenue is distributed because large
platforms control audience discovery, user data, advertising infrastructure and measurement.
Karnani, however, says the answer cannot be to abandon platforms altogether. “Publishers need to reduce
dependence on Big Tech for discovery and build their own ecosystems and direct audience relationships,” he says.
“Big Tech can remain a discovery engine, but publishers need to own the destination and the relationship.”
That could mean treating websites as only one part of the product, alongside apps, newsletters, WhatsApp
communities, video, events and specialised communities. The argument is less about escaping platforms and
more about not allowing discovery to become the same thing as ownership.
AI Adds a New Value Question
The next battleground could be even more fundamental: if journalism is increasingly being used to power AI
products and answers, who captures the value created by that content?
For publishers, that makes AI licensing part of a much larger question about the economics of journalism. If
search engines and AI systems can increasingly satisfy a user’s information need without sending that user to the
publisher’s website, the old advertising model comes under another layer of pressure.
Yet the experts also caution against interpreting falling traffic or weak display growth as evidence that audiences
have stopped consuming news. “The issue is not that the audience walked away. It is that publishers did not
follow them to where they went,” Amar says.
For news publishers, the next phase of digital monetisation may therefore depend less on producing more
inventory and more on proving why their audience is worth paying for — wherever that audience chooses to
consume the news
Courtsey:e4m